Larry Ellison Scraps Plan to Sell Up to 50 Million Oracle Shares Amid Market Volatility and Scrutiny

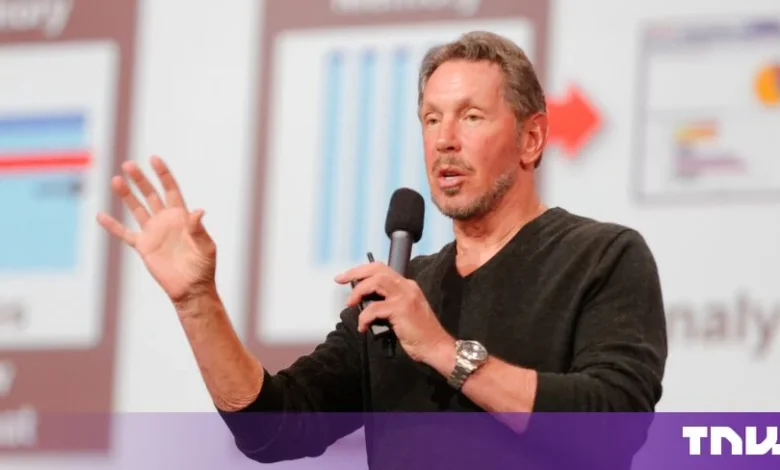
Oracle executive chairman and chief technology officer Larry Ellison has abruptly cancelled a pre-arranged trading plan that would have authorized the sale of up to 50 million shares of the company’s common stock. The decision to terminate the plan, which was originally slated to remain active until October 24, was formalized just one day after its public disclosure. According to official filings and statements from the corporation, no shares were liquidated under the arrangement during the brief window it existed.
The sudden reversal comes at a sensitive time for the Austin-based software giant. Oracle’s stock price has experienced significant downward pressure recently, shedding approximately 16% of its value since the plan was initially adopted on June 22. At the time of the plan’s inception, the 50 million shares were valued at roughly $8.75 billion; by the time the cancellation was announced, that valuation had contracted to approximately $7.5 billion.
The Mechanism of Rule 10b5-1
At the heart of this development is the Rule 10b5-1 trading plan, a mechanism established by the U.S. Securities and Exchange Commission (SEC) in 2000. These plans are designed to allow corporate insiders—who often possess non-public material information—to set up a predetermined schedule for selling company stock. By establishing these trades in advance, executives can theoretically insulate themselves from allegations of insider trading, as the decisions to buy or sell are dictated by a fixed formula rather than ongoing market conditions or immediate access to private data.
The SEC introduced significant reforms to these plans in 2022, mandating greater transparency, including "cooling-off" periods between the adoption of a plan and the first trade, and requiring enhanced disclosure of these arrangements. Despite these safeguards, the utility of such plans remains a subject of intense debate among market observers, particularly when major shareholders like Ellison—who maintains a controlling interest of roughly 40% in Oracle—utilize them during periods of corporate transition.
Chronology of Events
The timeline surrounding the plan’s adoption and subsequent cancellation highlights the volatility Oracle has faced in recent months:
- June 22: Larry Ellison formally adopts the Rule 10b5-1 trading plan, providing the authorization to sell up to 50 million shares.
- Early September: Oracle reports its latest financial results, characterized by a contraction in gross margins, sparking investor concern.
- Thursday, September 11: Following the earnings release, the market reacts negatively, and the company confirms it has increased its budget for job-cut-related costs to $2.8 billion.
- Friday, September 12: Oracle shares fall 1.7% in trading. The trading plan is publicly disclosed.
- Saturday, September 13: The plan is officially cancelled. Oracle issues a statement confirming that no shares were sold and that Ellison holds no current plans to dispose of his holdings.
Regulatory Disparities: US vs. EU
The incident has drawn attention to the fundamental differences between U.S. market oversight and European Union regulations. While Rule 10b5-1 provides a "safe harbor" for executives in the United States, European markets operate under a more rigid framework governed by the Market Abuse Regulation (MAR).
Under the EU’s MAR, individuals discharging managerial responsibilities are strictly prohibited from dealing in their company’s shares during a 30-day "closed period" preceding the publication of interim or year-end financial reports. Unlike the U.S. system, there is no "adopt-in-advance" exemption that would allow an executive to circumvent this blackout window.
Furthermore, the disclosure requirements differ significantly. In the EU, regulators prioritize the reporting of completed transactions rather than future intentions. Transactions must be disclosed within three working days once a cumulative threshold—typically EUR 5,000—is reached in a calendar year. Consequently, had Ellison been subject to European rules, the existence of his intended sell-off plan would likely never have been made public, as the plan itself resulted in no transaction.
Corporate Context and Market Sentiment
The cancellation of the sale occurs against a backdrop of financial uncertainty for Oracle. The company, which has been aggressively pivoting toward cloud infrastructure and artificial intelligence, is currently navigating a complex financial landscape. Analysts have pointed to a recent downgrade in the company’s credit outlook, with some agencies placing Oracle just one notch above "junk" status.
The increased costs associated with restructuring—specifically the $2.8 billion in anticipated severance and transition expenses—have compounded the pressure on the company’s bottom line. When combined with shrinking gross margins, investors have become increasingly sensitive to any signal from leadership regarding their confidence in the company’s long-term valuation.
Although Ellison’s decision to cancel the plan suggests a desire to avoid the optics of selling during a downturn, the company’s official statement was brief and matter-of-fact. "No Oracle stock was sold under that plan, and he has no other plans to sell any of his Oracle stock," a representative stated.
Implications for Governance and Disclosure
The scrutiny surrounding this event underscores the evolving expectations for corporate transparency. While Ellison’s actions remained entirely within the letter of the law—and the disclosure of the plan itself was a result of the very transparency rules designed to protect the market—the incident highlights the tension between executive liquidity needs and investor perception.
For institutional investors, the primary concern is often the stability of leadership commitment. When an executive controlling 40% of a firm prepares to liquidate a significant portion of their stake, it can be interpreted as a lack of confidence, regardless of the underlying financial planning reasons. By cancelling the plan, Ellison has effectively quelled immediate market speculation, but the episode serves as a reminder of the magnifying glass under which tech titans operate.
Moreover, the discrepancy between the U.S. and European regulatory regimes poses a recurring challenge for multinational corporations. As global markets become more interconnected, the calls for a unified approach to insider trading and disclosure are likely to grow. The current U.S. approach, while flexible, relies heavily on the "honor system" of pre-arranged plans, whereas the European model emphasizes strict, time-based prohibitions.
Analysis of Future Market Behavior
Looking forward, analysts expect Oracle to continue its focus on AI-driven revenue growth to offset the costs of its restructuring efforts. The company’s ability to stabilize its gross margins will be the key metric for shareholders in the coming quarters.
Regarding insider trading, the incident is unlikely to change the legal standing of Rule 10b5-1 plans, but it may prompt boards of directors to exercise greater oversight regarding the timing of when these plans are adopted. When an executive of Ellison’s stature adopts a plan, the potential for market disruption is high, and companies may increasingly look to implement internal "quiet periods" that go beyond what the SEC currently requires.
Ultimately, the cancellation of the sale has prevented what could have been a contentious moment for Oracle’s shareholder base. By opting to hold his shares, Ellison maintains his status as the company’s most significant stakeholder, signaling, at least for the time being, that his interests remain aligned with the long-term trajectory of the software giant. Whether this serves as a temporary pause or a permanent abandonment of his divestment strategy remains to be seen, but for now, the market has responded with a degree of stability, signaling that the immediate uncertainty has been cleared from the docket.
Related posts: