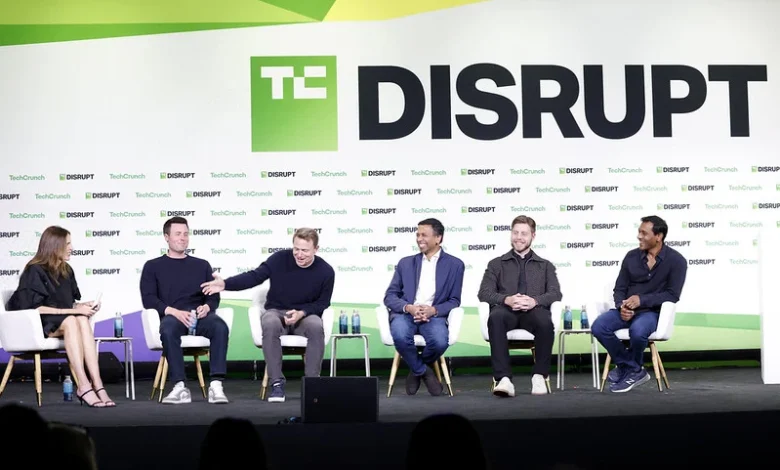
The venture capital landscape is undergoing a tectonic shift, marked by surging valuations, gargantuan mega-funds, and a relentless race to dominate the artificial intelligence ecosystem. Yet, amidst this hyperactive gold rush, storied Silicon Valley venture capital firm Benchmark continues to march to the beat of its own historic drum. During a highly anticipated appearance at TechCrunch Disrupt, all five of Benchmark’s general partners took the stage to offer a rare, collective glimpse into how the 31-year-old firm operates in an era defined by extreme technological acceleration and economic uncertainty.
While the broader venture capital industry races to scale operations, deploy billions into speculative AI startups, and expand headcounts into the dozens or hundreds, Benchmark’s core philosophy remains stubbornly countercultural. The firm still limits its general partners to just two or three new investments per year, maintains a strict policy of holding Monday partner meetings without a structured agenda, and operates on an equal-partner model devoid of rigid hierarchies or corporate bureaucracy.
This deliberate friction against industry norms comes at a time of profound internal and external evolution for the firm. Over the past three decades, Benchmark has carefully guarded its reputation as a boutique, high-conviction early-stage investor. However, shifting macroeconomic realities and the immense capital requirements of modern tech infrastructure have forced the firm to adapt. Most notably, Benchmark recently announced a staggering $2 billion capital commitment split across two funds, marking only the second time in its three-decade history that it has deviated from its traditional, smaller vehicle size.
Main Facts and the Evolution of Benchmark’s Strategy
To understand Benchmark’s current positioning, one must examine its structural adjustments. For two decades, the firm kept its core early-stage fund capped at $500 million. According to general partner Peter Fenton, holding that line for so long while the broader economy inflated was ultimately a tactical error. The recent recalibration of their core fund aims to bring it in line with modern economic realities, ensuring they can continue making 10-to-15-year commitments to founders shoulder-to-shoulder.
Simultaneously, the introduction of Benchmark’s new $1.25 billion growth fund represents a calculated expansion of the firm’s mandate. Historically, successful portfolio companies that required massive late-stage capital injections would outgrow Benchmark’s early-stage focus, forcing the firm to watch potential 10x to 1,000x returns slip away. By launching a dedicated growth fund, Benchmark is carving out a pathway to capture that subsequent value creation.
Despite the larger pool of capital, Fenton emphasizes that the deployment strategy remains intensely concentrated. Drawing on the principles of power-law dynamics—echoed in recent financial literature highlighting the "agony and ecstasy" of concentrated portfolios—Benchmark expects just a handful of investments to drive the vast majority of the fund’s eventual returns. Rather than spraying capital across dozens of late-stage bets, the growth fund will likely target a tight-knit group of four to eight companies.
Chronology and Historical Context
Benchmark’s journey began 31 years ago, establishing itself as a dominant force through legendary early-stage bets on companies like eBay, Twitter, Uber, and Snapchat. Over the decades, the firm has witnessed numerous market cycles, dot-com bubbles, and financial crises. Yet, its personnel and structural discipline have continuously evolved.
The composition of Benchmark’s partnership has seen notable generational turnover. A mere three years prior to their Disrupt appearance, a sit-down with four of the firm’s partners revealed a vastly different lineup, with three of those individuals having since departed. The influx of new talent has brought fresh perspectives while preserving the firm’s foundational DNA.
In February, tech entrepreneur and podcast host Jack Altman joined the partnership, transitioning from an individual angel investor to a general partner at a legacy institution. Altman’s integration underscores Benchmark’s allure for top-tier operators navigating an increasingly chaotic market. Similarly, general partner Ev Randall—who previously worked at prominent institutions like Founders Fund, Bond, and Kleiner Perkins—noted that he was immediately drawn to Benchmark’s lean structure. Unlike large, federated venture operations with 50-to-60-person teams making decisions through Byzantine corporate processes, Benchmark relies on the high-fidelity, peer-to-peer communication possible only within a small, highly aligned sports-team-like unit.
The Monday Meeting Ethos and Internal Governance
A defining element of Benchmark’s mystique is its weekly Monday partner meeting, which famously operates without an agenda. Rather than tracking deals through rigid Customer Relationship Management (CRM) software or voting via formal matrices, the five general partners engage in an organic, decades-long conversation about technological possibility.
Eric Vishria explains that in times of rapid paradigm shifts—such as the sudden viability of technological capabilities that were impossible mere months ago—systematizing the evaluation process is counterproductive. The lack of bureaucracy allows partners to remain entirely reactive to founder needs, whether that means deploying the entire five-person collective to help recruit a C-suite executive or vetting complex strategic partnerships.
When pressed on whether a single partner can veto a deal, the response highlights the organic trust within the room. There are no explicit rules or voting thresholds. Because the firm’s aggregate deal volume is intentionally low, the lack of structural bureaucracy functions as a massive asset. Furthermore, Fenton notes that if an entrepreneur presents a polarizing vision and even one partner feels a misalignment, the firm walks away. Benchmark refuses to function like a televised pitch competition, recognizing that a founder-VC relationship requires absolute mutual admiration.
Navigating the AI Era: Volatility, Hysteria, and Market Realities
The panel offered pointed commentary on the current artificial intelligence frenzy, addressing widespread concerns regarding market overextension, skyrocketing capital expenditures, and valuation volatility. The discourse surrounding AI infrastructure has been dominated by fears of an impending bubble, exacerbated by recent events such as the high-profile bankruptcy of interactive chatbot platform Character.AI just five years after its inception.
Addressing these macro concerns, Ev Randall argued that the broader financial media and public equity markets frequently misinterpret isolated corporate restructuring as a systemic indictment of the AI ecosystem. Character.AI, for instance, had previously undergone a massive structural transition when its core team and founder were acqui-hired by Google, leaving the remaining corporate shell behind. Randall contends that public market volatility is heavily amplified by hyperactive echo chambers on social media platforms like X, where anonymous accounts frequently distort the true financial health of foundational AI leaders like OpenAI and Anthropic.
Despite these external anxieties, Benchmark’s portfolio companies report unprecedented commercial demand. Founders are routinely constrained not by a lack of paying customers or gross margins, but by a severe shortage of compute resources required to service incoming demand. According to Benchmark, the underlying fundamentals of the AI revolution remain robust; the true pathology lies in the market hysteria driven by clickbait data points and unverified projections.
The San Francisco Gravity Well
As the epicenter of the global technology industry aggressively re-concentrates around San Francisco, the partners weighed in on whether geographic proximity remains a strict prerequisite for startup success. Jack Altman observed that while exceptional companies can occasionally emerge from disparate regions—pointing to historical outliers like Shopify—San Francisco currently offers an unmatched density of talent, specialized capital, and early adopters.
Peter Fenton reinforced this sentiment with historical data, noting that upwards of 90% of the firm’s historical capital returns have originated from companies founded within the immediate Bay Area ecosystem. The self-reinforcing flywheel of successful alumni, dense executive networks, and hyper-ambitious peers continues to raise the bar of technological execution in a manner that has not been successfully replicated anywhere else globally.
Broader Impact and Industry Implications
Benchmark’s deliberate choice to resist the siren song of hyper-scaling offers a fascinating case study for the broader venture capital asset class. As institutional limited partners increasingly demand massive fund sizes and rapid deployment schedules, firms like Benchmark demonstrate that extreme concentration, low deal volume, and rigorous interpersonal alignment remain viable—and highly lucrative—counter-strategies.
By maintaining a tight lid on portfolio expansion, safeguarding partner cohesion, and leaning heavily into unorthodox, polarizing founders—as seen in their early-stage conviction in semiconductor pioneer Cerebras—Benchmark continues to prove that patience and craft can still yield extraordinary returns in a world obsessed with speed. As the AI landscape matures through its inevitable turbulence, the firm’s unwavering adherence to its foundational playbook serves as both an anchor and a challenge to an industry constantly tempted to chase momentum over substance.