Insta360 Shifts Global Strategy as Industry Consolidation and Memory Crises Redefine the Action Camera Market

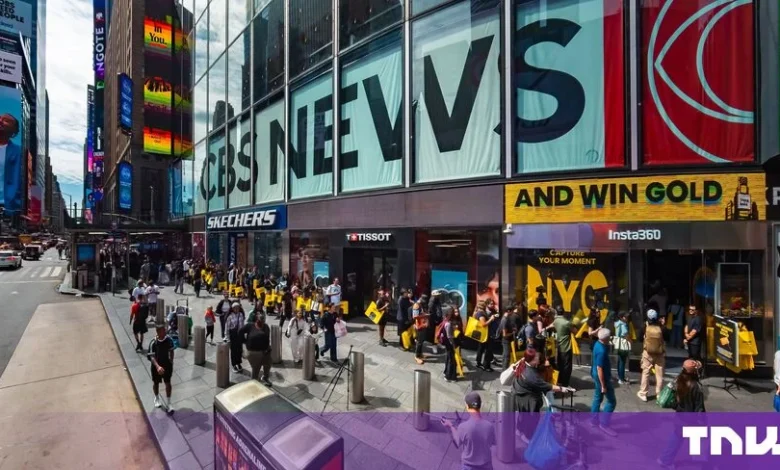
Insta360 has officially marked a significant milestone in its international expansion by opening its first American flagship store at 1515 Broadway in the heart of New York City’s Times Square. This high-profile launch, which took place this past Saturday, serves as more than just a retail footprint; it acts as a physical manifestation of the company’s current dominance in a sector that is undergoing a period of intense, tech-driven volatility. This location represents only the second self-operated retail storefront for the Shenzhen-based camera manufacturer outside of China, following the inauguration of its Tokyo branch in August.
While the ribbon-cutting ceremony drew the attention of tourists and tech enthusiasts alike, the underlying industry dynamics paint a much more complex picture of survival and strategic maneuvering. Co-founder Max Richter recently detailed these challenges in an interview, highlighting that the action camera market is being fundamentally reshaped by two uncontrollable external forces: a global scarcity of consumer memory chips and a tightening regulatory environment for Chinese technology firms.
The Financial Toll of the Memory Crunch
The current state of the industry is perhaps best illustrated by the disparity in capital allocation toward hardware components. In the first half of 2024 alone, Insta360 reported an expenditure of nearly 2 billion yuan (approximately $298.4 million) on the strategic procurement of memory chips. Richter has signaled that a similar, if not greater, financial burden is anticipated for the coming quarters, as the timeline for the alleviation of the global memory crisis remains dangerously opaque.
This massive capital outlay serves as a stark differentiator when compared to the struggles of Western incumbents. GoPro, once the undisputed leader of the action camera market, recently reached a definitive agreement to merge with Starman Optical on September 1. Under the terms of the deal, GoPro shareholders are set to receive $285 million in cash, valued at $1.14 per share, while maintaining a minority stake of roughly 10% in the restructured entity. Furthermore, Starman Optical will assume approximately $92 million of GoPro’s outstanding debt.
The comparison is striking: the amount of capital Insta360 has had to commit to securing essential memory components over a six-month window is roughly equivalent to the total acquisition price of its primary American rival. This disparity highlights the "sorting mechanism" that the current memory crisis has become—a test of corporate liquidity and the ability to absorb significantly inflated input costs while maintaining operations.
Comparative Performance: Resilience vs. Retrenchment
The shockwaves from the AI data center boom—which has diverted wafer capacity away from consumer electronics—have impacted both firms with equal force. However, the balance sheets of the two companies tell very different stories.
Insta360 has managed to remain profitable, though the margin for error has narrowed significantly. Its most recent half-year financial report indicates a 50% surge in revenue, which was paradoxically accompanied by a 94% decline in net profit. This squeeze is the direct result of the astronomical rise in memory chip costs combined with an aggressive 80% increase in research and development spending. By choosing to prioritize innovation and volume, Insta360 has essentially sacrificed short-term profitability to ensure it remains the dominant player in the hardware space.
Conversely, GoPro proved unable to weather the storm. The company cited a devastating 80% to 115% increase in memory costs, which, combined with a 26% decline in revenue and the looming threat of covenant breaches, forced it into a defensive position. The subsequent workforce reduction of 23% and the eventual search for a buyer demonstrate the critical difference between a company that can sustain a long-term strategy of capital expenditure and one that is fundamentally broken by the same market conditions.
The Strategic Pivot: GoPro’s New Identity
The irony of the GoPro acquisition is that the firm is being absorbed into the very sector that caused its collapse. As part of the merger, GoPro is set to pivot away from its traditional consumer-facing identity. Founder Nicholas Woodman has stated that the merged entity will focus on the aerospace, national security, government, and AI data center imaging markets. By realigning as an "American imaging and optical company," the firm hopes to leverage its remaining intellectual property in sectors that are currently seeing massive government investment. The deal is expected to conclude by the end of the year, provided that regulatory bodies and shareholders provide the necessary approvals.
Regulatory Hurdles and the DJI Factor
While the memory crisis has claimed one casualty, the regulatory landscape has created a different kind of barrier for another major rival, DJI. In December 2025, following a security audit ordered by the U.S. Congress, the Federal Communications Commission (FCC) placed DJI on its "covered list." This move effectively halted the approval of any new DJI products for import or sale within the United States.
While existing inventory remains on store shelves, the "freeze" creates a compounding problem for the company: as product cycles progress, DJI finds itself unable to introduce new, competitive models to the American market. The potential for the situation to escalate is high, with the FCC proposing the possibility of retroactively pulling authorization for previously approved drones that utilize thermal imaging, LiDAR, or docking capabilities.
When questioned about his competitor’s regulatory predicament, Max Richter maintained a professional, cautious stance. He noted that Insta360 is not currently subject to similar restrictions and emphasized that the company does not view the lockout of a competitor as a "windfall." Richter’s rhetoric is a carefully calculated effort to avoid drawing unnecessary scrutiny; however, the reality of the geopolitical landscape is that the "covered list" is expanding across categories, including robotics and power inverters, creating a precarious environment for all Shenzhen-based manufacturers with cloud-connected devices.
Market Share and the Logic of Physical Retail
According to data from IDC for the first quarter, DJI maintains a 65% share of the global handheld smart camera market, with Insta360 trailing at 22%. However, this gap is increasingly viewed as deceptive when growth rates are analyzed. Insta360 recorded a 66% year-on-year growth in shipments, far outpacing DJI’s 38%. In the specific niche of 360-degree cameras, Insta360 holds a commanding 68% market share, having surpassed a cumulative total of 10 million units shipped since its inception in 2015.
The commitment to a multi-year lease in Times Square is a strategic wager that the company’s growth trajectory will continue to outperform the market. Richter explains that the store is designed as an educational hub rather than a traditional sales floor. Because the "invisible selfie stick" effect and the unique perspective of 360-degree footage are difficult to convey via digital listings, the company requires a physical environment where potential users can experience the product firsthand.
Beyond product demonstration, the flagship store is a statement of intent. By moving away from a pure price war—a conflict that currently defines its competition with DJI in the Chinese domestic market—Insta360 is attempting to establish itself as a premium brand driven by innovation rather than commodity pricing.
Future Outlook and Industry Watchpoints
As the year draws to a close, market analysts are keeping a close watch on three specific indicators for the industry.
First, the "memory line" in upcoming earnings reports will be the primary metric for survival. If Insta360’s revenue growth of 50% continues to be outpaced by its 2 billion yuan procurement costs, the company may eventually be forced to raise prices, which could dampen its current growth trajectory.
Second, supply chain diversification will be a major point of interest. There is growing evidence that domestic Chinese DRAM manufacturers, such as CXMT, are beginning to supply components for Western-market electronics. As a Shenzhen-based firm, Insta360 possesses a logistics and supply chain advantage in accessing these components compared to its Western or internationally-based competitors.
Finally, the regulatory environment remains the most unpredictable variable. While Insta360 is currently operating without restriction, Richter’s careful phrasing—specifically his use of the word "currently"—acknowledges that the policy landscape for Chinese technology in the United States is fluid. Whether the company can continue its expansion into Europe—with new stores planned for Munich and Amsterdam—while navigating the tightening security requirements of the Western world will determine if the "Times Square bet" pays off in the long term. For now, the action camera market is being filtered by those who have the capital to endure the silicon drought and the diplomatic flexibility to survive in a bifurcated global economy.