UK Government Proposes VAT Shift for Online Marketplaces to Level Playing Field for High Street Retailers

The United Kingdom government is moving toward a significant overhaul of its Value Added Tax (VAT) collection framework, targeting the digital marketplace sector to address long-standing concerns regarding tax evasion and market imbalances. Under the proposed legislative shift, major e-commerce platforms would be mandated to collect and remit VAT on behalf of larger domestic sellers, a responsibility currently confined primarily to overseas traders. This policy adjustment, which is expected to be a centerpiece of the upcoming Autumn Budget, aims to secure up to £1 billion in annual revenue for the Treasury. These funds are earmarked to finance relief measures for high street businesses, which have faced mounting pressure from a surge in low-cost online competition.
The Evolution of VAT Regulation in Digital Commerce
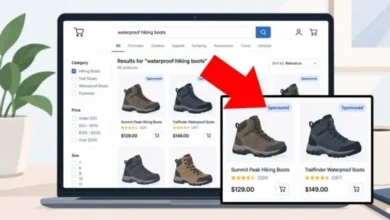
The landscape of online retail taxation in the United Kingdom has undergone rapid transformation over the past decade as the government has struggled to keep pace with the digitalization of commerce. Historically, the burden of VAT collection fell upon individual merchants. However, the rise of global marketplaces created a "grey market" where foreign entities could leverage UK-based fulfillment centers while circumventing tax obligations.
In 2021, the government implemented the first major legislative step in this direction, forcing online marketplaces to become "deemed suppliers" for sales made by overseas sellers. While this move succeeded in curbing some forms of blatant tax avoidance, it inadvertently highlighted a new loophole. Sophisticated operators began utilizing shell companies—often established by foreign nationals—to register as UK-based businesses. By obtaining valid UK VAT numbers and maintaining the facade of domestic operations, these entities could continue to undercut local retailers while systematically avoiding tax payments through a "phoenixing" strategy, where companies are dissolved before the tax bill becomes payable to His Majesty’s Revenue and Customs (HMRC).
Proposed Thresholds and Implementation Challenges
The current proposal under consideration by the Treasury seeks to expand the "deemed supplier" rule to include domestic sellers who exceed a specific revenue threshold. Reports suggest that the government is evaluating a threshold of £90,000 in annual sales per platform. The logic behind this figure is to capture high-volume professional sellers while exempting smaller, artisanal, or hobbyist traders who might find the administrative burden of such a system prohibitive.
However, the implementation of this threshold faces significant scrutiny from tax experts and industry watchdogs. Critics argue that a rigid £90,000 limit could inadvertently incentivize "tax engineering." Sellers might attempt to circumvent the requirement by fragmenting their business operations across multiple accounts or diversifying their presence across several competing platforms, each falling just beneath the reporting threshold. To mitigate this, the Treasury would likely need to develop robust data-sharing protocols that allow HMRC to aggregate seller data across the entire e-commerce ecosystem.
The High Street Crisis and Economic Strategy
The push for this tax reform is deeply rooted in the government’s broader economic strategy to revitalize the British high street. Prime Minister Andy Burnham and his administration have frequently characterized family-owned businesses as the "heart and soul" of the national economy. Yet, these physical retailers have been hampered by high business rates, overhead costs, and an inability to compete with the pricing structures of online entities that have successfully sidestepped the 20 percent VAT levy.
The Treasury faces an exceptionally tight fiscal environment, with limited room for broad-based tax cuts. By capturing an estimated £700 million to £1 billion annually in previously uncollected VAT, the government hopes to create a "revenue-neutral" mechanism. In this model, the tax collected from online platforms would be directly channeled into reducing the business rates burden for brick-and-mortar stores. This is viewed not merely as a tax collection exercise, but as an essential intervention to prevent further erosion of town centers and to ensure that competition between digital and physical retail is conducted on an equitable basis.
Industry Perspectives: The Role of Marketplaces
The major players in the digital retail space have largely adopted a conciliatory stance toward the proposed regulations. Amazon, which serves as the primary conduit for many of the affected sellers, has signaled its willingness to cooperate with the new mandates. Industry analysts suggest this cooperation stems from a desire to mitigate reputational risk; as global platforms face increasing scrutiny from regulators regarding the ethics of their supply chains, being seen as a partner in tax compliance provides a strategic advantage.
Amazon has publicly indicated that the changes could indeed generate significant revenue for the state, with their internal estimates aligning with the Treasury’s projection of approximately £700 million. By centralizing the collection process, these platforms can leverage their sophisticated automated systems to ensure compliance, effectively automating a process that HMRC has historically found difficult to monitor manually.
Chronology of Legislative Developments
- 2021: The UK government implements the "deemed supplier" rule, forcing marketplaces to collect VAT on behalf of non-UK sellers.
- 2022-2023: Evidence mounts regarding the proliferation of UK-registered shell companies used by foreign nationals to evade VAT, leading to investigations by the Public Accounts Committee.
- Early 2024: Treasury officials begin formal consultations with e-commerce platforms regarding the extension of tax collection duties to domestic sellers.
- October 2024: Chancellor John Healey is scheduled to present the Budget, where the final details of the threshold and implementation timeline are expected to be unveiled.
Analyzing the Broader Economic Implications
The transition to a mandatory collection model for domestic sales represents a fundamental shift in the relationship between the state, the platform, and the seller. If enacted, this policy will effectively transform e-commerce platforms into "de facto" tax collectors for the UK government. While this ensures a higher degree of tax compliance, it also imposes a higher administrative cost on the platforms, which may ultimately be passed down to consumers through increased service fees or adjusted commission rates for third-party sellers.
Furthermore, the impact on the UK’s SME (Small and Medium-sized Enterprise) sector cannot be overstated. For many small retailers, the marketplace is their primary gateway to the national market. If the regulatory environment becomes too complex, there is a risk that smaller domestic businesses may struggle to adapt, potentially stifling innovation and growth within the digital economy.
However, the counter-argument remains compelling: the current system, characterized by widespread VAT evasion, creates an artificial price advantage for foreign sellers that domestic retailers cannot bridge through efficiency or product quality alone. By closing the "shell company loophole," the government aims to restore market integrity.
Conclusion: The Path to the Autumn Budget
As the October 28 Budget approaches, all eyes are on Chancellor John Healey. The success of this policy will depend heavily on the fine print—specifically how the government plans to define "domestic seller" and whether the £90,000 threshold will be sufficient to catch high-volume evaders without placing an undue burden on legitimate small businesses.
The integration of advanced data analytics and the continued cooperation of dominant marketplaces like Amazon and eBay will be critical to the success of this measure. If successful, the reform could serve as a blueprint for other nations grappling with the challenge of taxing globalized, platform-based retail. For now, the proposal stands as a clear signal of intent: the era of tax-free competitive advantage for digital platforms in the United Kingdom is coming to a close, as the government prioritizes the stabilization of the physical high street and the restoration of a level playing field for all taxpayers.